
– By Dilip Davda
- The company is engaged in providing payment solutions, identifications solutions, secure solutions, smart tagging etc. for BFSI segment.
- It enjoys most preferred partner in payment card segment across the user industry.
- Based on its recent average financial data, the issue appears fully priced.
- With digitization and securitization of payment process, it is heading for bright prospects.
- Investors can park funds for medium to long term rewards.
ABOUT COMPANY:
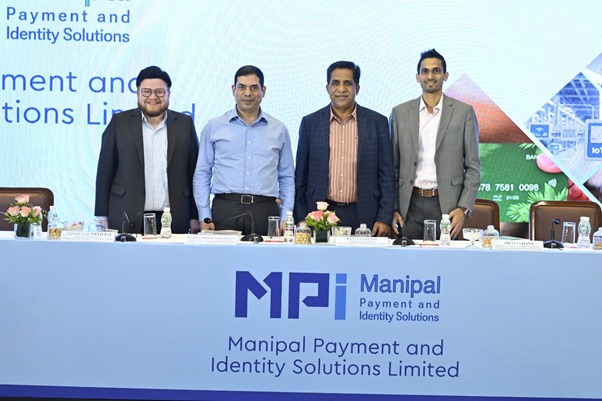
Manipal Payments & Identity Solutions Ltd. (MPISL) provides payments solutions, identifications solutions, secure solutions, and smart tagging and internet of things (“IOT”) solutions to banks, fintechs, non-banking finance companies and governments, across domestic and international jurisdictions. Incorporated on February 19, 2008, the Company is part of The Manipal Group. The Manipal Group commenced operations in 1948 as a printing company, under the name of Express Printers Private Limited, catering to the secured printing requirements of banks in India and has since added products and services catering to customer requirements across various industries.
Its payment solutions primarily comprise payment cards, cheque solutions, near-field communication (“NFC”)/quick response (“QR”) codes, payment-enabled wearables, and digital automation solutions. Its identification solutions primarily comprise driving licenses, registration certificates, national identity cards, among others, along with transit management solutions. Its secure solutions primarily comprise secure logistics, personalization of insurance policies, premium notices, renewal letters and marketing collaterals, along with security-enhanced packaging such as tamper-evident envelopes, holograms and coated products. Its smart tagging and IOT solutions primarily entail printing of excise labels with holograms and encrypted QR codes for various state excise departments, IOT and track and trace solutions with radio-frequency identification (“RFID”) tags, and anti-counterfeiting solutions.
The Company had an estimated market share of approximately 36.4% in the credit card issuance market and 30.9% in the debit card issuance market in India for Fiscal 2026, having billed 13.54 million credit cards and 72.66 million debit cards during Fiscal 2026. It is among the largest manufacturers of payment cards, both globally and in India in Fiscal 2026. It pioneered the manufacturing of National Common Mobility Cards in 2024 in partnership with Airtel Payments Bank and also launched India’s first recyclable polyvinyl chloride (“rPVC”) Rupay card in 2024. Further, as of March 31, 2026, it is one
of the leading metal card manufacturers in India holding a patent for metal cards manufacturing. As of March 31, 2026, it supplied metal cards to the top four credit cards issuers in India. It is one of the largest manufacturers of dual interface (“DI”) cards in India in Fiscal 2026. (Source: F&S Report)
MPISL is the highest ranked company in India and 14th ranked company globally in terms of shipment of payment cards with chips and magstripe in 2023, and among the top 10 card manufacturers for Mastercard and another payment network globally in 2023. (Source: F&S Report) As of March 31, 2026, it is one of the largest producers of national identity cards in India, having successfully billed over 1 billion cards in 12 regional languages. It also pioneered the manufacturing of India’s polycarbonate-based driving license cards using specialized ink, along with registration certificates. The company is among the select partners to get engaged for projects like polycarbonate-based ID cards, in compliance with guidelines of the Ministry of Road Transport and Highways (“MORTH”). It has successfully deployed India’s large-scale instant issuance kiosk solution, rolling out over 500 kiosks simultaneously for State Bank of India. (Source: F&S Report) It has been associated with transport authorities in Maharashtra and Chhattisgarh for issuing registration certificates and driving licenses in these regions.
MPISL catered to a diverse set of over 300 customers in Fiscal 2026 across domestic and international jurisdictions. In the last three Fiscals, it has exported products such as credit cards, debit cards and metals cards to countries including UK, Singapore, Bahrain, Hong Kong, Oman, Maldives, Mauritius, South Africa, Bangladesh, Brazil, Nigeria, Nepal, Sri Lanka, Bolivia and United Arab Emirates, as well as certain countries in Europe. Its customers for payment cards include private sector banks, public sector banks (“PSBs”), small finance banks, payment banks, co-operative banks, prepaid payment instrument license holders and fintechs. Additionally, the company also supports government initiatives by supplying secure identification cards, tax stamps, and other essential documents. Its commitment to customer satisfaction is evident through its tailored technology driven solutions, stringent security measures, continued compliances and continuous efforts to enhance operational efficiency.
The company has a history of being certified for its operations by payment networks including Mastercard (over 16 years), RuPay (over 9 years) and by other payment networks for over 15 years and 9 years, respectively, for manufacturing and personalization of payment cards. Further, its facilities are certified for Payment Card Industry Data Security Standard (“PCIDSS”) (Level 1) Version 4.0.1 for secure data management and its Manipal Facility is certified for ‘INTERGRAF’ (Central Bank Level) and Card Quality Management for secure card manufacturing and personalization. These certifications are a testament to its continued compliance with standards for IT and cyber security and physical security.
Acquiring these certifications serves as an entry barrier towards manufacturing payment cards, and places it among a league of manufacturers equipped to offer payment cards. As of the date of this Red Herring Prospectus, it serves customers through 10 facilities across India. These include one card manufacturing facility and personalization bureau in Manipal Karnataka, one card manufacturing facility and cheque printing facility in Manipal, Karnataka, one personalization bureau in Navi Mumbai, Maharashtra, one personalization bureau and cheque printing facility each in Noida, Uttar Pradesh and Chennai, Tamil Nadu, one cheque printing facility each in Navi Mumbai, Maharashtra and Howrah, West Bengal; and three facilities for smart tagging and IOT solutions along with coated products business in the states of Manipal, Karnataka and Bengaluru, Karnataka. As of Marach 31, 2026, it had 1809 employees on its payroll and additional 1509 contractual employees.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO of approx. 23746313 equity shares (worth Rs. 805 cr.at the upper cap). The IPO consists of fresh equity shares worth Rs. 320.00 cr. (approx. 9439528 equity shares at the upper cap) and an Offer for Sale (OFS) of 14306785 equity shares (worth Rs. 485 cr. at the upper cap). The company has announced a price band of Rs. 322 – Rs. 339 per equity shares of Rs. 2 each. The issue opens for subscription on September 09, 2026, and will close on September 11, 2026. The minimum application to be made is for 44 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 10.24% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 238.43 cr. for capex on purchase of equipments, and the rest for general corporate purposes.
The five joint Book Running Lead Managers (BRLMs) to this issue are Motilal Oswal Investment Advisors Ltd., Axis Capital Ltd., ICICI Securities Ltd., IIFL Capital Services Ltd., and Nuvama Wealth Management Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Motilal Oswal financial Services Ltd., and Nuvama Wealth Management Ltd. are syndicate members.
The company has issued/converted entire initial equity shares at par value. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 2.18 per share.
Post-IPO, its current paid-up equity capital of Rs. 44.47 cr. (222365000 equity shares) will stand enhanced to Rs. 46.36 cr. (231804528 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 7858.17 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit, of Rs. 1267.97 cr. / Rs. 249.17 cr. (FY24), Rs. 1277.11 cr. / Rs. 282.21 cr. (FY25), and Rs. 1356.59 cr. / Rs. 253.46 cr. (FY26). The company posted steady growth in its top line, but bottom line marked a setback for FY26. Its contingent liability stood at Rs. 130.78 cr. as of March 31, 2026 and raise alarm. Rising trade receivables year-on-year raise concern.
For the last three fiscals, the company has posted an average EPS of Rs. 12.32 (basic) and an average RoNW of 36.90 %. The issue is priced at a P/BV of 6.94 based on its NAV of Rs. 48.84 as of March 31, 2026, and at a P/BV of 5.61 based on its post-IPO NAV of Rs. 60.46 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 31.02. Based on FY25 earnings, the P/E stands at 27.86. The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 19.65% (FY24), 22.10% (FY25), 18.68% (FY26), and RoCE margins of 51.95%, 33.97%, 32.69%, respectively, for the referred periods.
DIVIDEND POLICY:
The company paid a dividend of 10% for FY24, and thereafter it skipped. It has already adopted a dividend policy in June 2025, based on its financial performance and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Seshaasai Technologies, as its listed peer. It is currently trading at a P/E of 23.1 (as of September 04, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The five BRLMs associated with this issue has handled 137 IPOs in the last three fiscals and out of which 39 IPOs closed below the issue price on listing date.
CONCLUSION:
MPISL is engaged in providing payment solutions, identifications solutions, secure solutions, smart tagging etc. for BFSI segment. It enjoys most preferred partner in payment card segment across the user industry. Based on its recent average financial data, the issue appears fully priced. With digitization and securitization of payment process, it is heading for bright prospects. Investors can park funds for medium to long term rewards.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
