
– By Dilip Davda
- The company is a real estate developer present across the full spectrum of realty development.
- It posted inconsistency in its financial performance for the reported periods.
- It ranked third in terms of new launches and sales in Mumbai.
- It is operating in a highly competitive segment.
- Based on its recent average financial data, the issue appears aggressively priced.
- There is no harm in skipping this pricey bet.
ABOUT COMPANY:
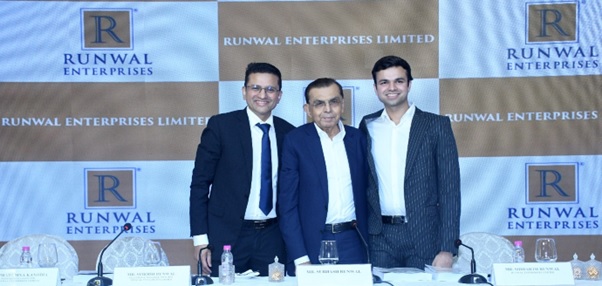
Runwal Enterprises Ltd. (REL) is a real estate developer present across the full spectrum of real estate development, specializing in residential projects that cater to affordable, mid-income, and luxury segments, as well as commercial spaces, retail malls and educational buildings. (Source: JLL Report) It is a recognized brand in the industry and have a strong presence in Mumbai. (Source: JLL Report)
REL ranked third in terms of new launches and sales in Mumbai with approximate market shares of 2.33% and 2.46%, respectively, between January 2023 and March 31, 2026. (Source: JLL Report) Between January 2023 and March 2026, Mumbai was ranked first among the top seven Indian residential real estate markets (i.e., Mumbai, Pune, Bengaluru, Hyderabad, Delhi National Capital Region, Chennai and Kolkata) in terms of its contribution to market activity, accounting for approximately 24% of the overall sales, approximately 24% of the overall new launches and overall sales value in India. (Source: JLL Report)
In the eastern suburbs’ submarket of Mumbai (which encompasses Mulund, Vikhroli, Ghatkopar, Kanjurmarg, Powai and Bhandup), it ranked first in sales accounting for approximately 7.88% of the sales, and fourth in new launches, accounting for approximately 2.89%, between January 2023 and March 31, 2026. (Source: JLL Report) It is ranked first in terms of new launches and second in terms of sales in Kalyan, Dombivli, with approximate market shares of 11.41% and 6.33%, respectively, between January 2023 and March 31, 2026. (Source: JLL Report)
As of March 31, 2026, it had 19 Completed Projects, 28 Ongoing Projects and 33 Upcoming Projects. Its experience includes greenfield projects requiring land acquisition, as well as flexible models and asset light models such as via joint development agreements (“JDA”). Greenfield projects refer to developments undertaken on land parcels that have never been previously used, developed or constructed upon for residential dwelling purposes. For such projects, the company acquires the greenfield land, obtain all necessary regulatory, statutory and environmental approvals required under applicable laws and it subsequently plans, designs and develops the project, including undertaking construction and related activities.
REL’s real estate development business spans all activities related to real estate development, from the identification and acquisition of land through to the planning, execution, marketing and sales of development projects. It is through this process that it develops a variety of residential and commercial projects comprising apartments, retail spaces, offices, schools, hospitals, and townhalls. As of March 31, 2026, it had developed and are in the process of developing an aggregate Developable Area of 31.96 million square feet of residential, retail and commercial properties, which include residential buildings, townships, corporate offices, retail malls, retail spaces, schools and various other real estate projects spread across the eastern, central, peripheral central, south central and western suburbs of Mumbai.
REL’s vision is to be a full-service real estate developer in Mumbai, developing both residential and non-residential projects (across the price spectrum) and in communities (including integrated townships) that feature a wide range of amenities and iconic landmarks. As of March 31, 2026, it had 1181 employees on its payroll.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route IPO worth Rs. 500.00 cr. (of approx. 16393443 equity shares at the upper cap). The company has announced a price band of Rs. 290 – Rs. 305 per equity shares of Rs. 2 each. The issue opens for subscription on September 25, 2026, and will close on September 29, 2026. The minimum application to be made is for 49 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 11.09% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 100.00 cr. for repayment/prepayment of certain borrowings, Rs. 225.00 cr. for investment in its wholly owned material subsidiaries namely Runwal Residency Pvt. Ltd., and Evie Real Estate Pvt. Ltd., and the rest for funding future real estate projects / general corporate purposes.
The company has reserved equity shares worth Rs. 3.50 cr. (approx. 114754 shares at the upper cap), and offering them a discount of Rs. 14 per share. From the rest, it has allocated not more than 50% for QIBs, not less than 35% for Retail Investors and not less than 15% for HNIs.
The two joint Book Running Lead Managers (BRLMs) to this issue are ICICI Securities Ltd., and Jefferies India Pvt. Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. BRLMs are also syndicate members.
After issuing initial equity shares at par value, the company has converted 1500 CCDs into equity shares at a pre-defined price (on the basis of Rs. 2 FV), in August 2026. The company also issued bonus shares in the ratio of 2500 for 1 in February 2021. The average cost of acquisition of shares by the promoters is Rs. NIL per share.
Post-IPO, its current paid-up equity capital of Rs. 26.28 cr. (131391436 equity shares) will stand enhanced to Rs. 29.56 cr. (147784879 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 4507.44 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 2436.68 cr. / Rs. 93.70 cr. (FY24), Rs. 1050.71 cr. / Rs. 55.65 cr. (FY25), and Rs. 1850.79 cr. / Rs. 185.76 cr. (FY26). While it posted inconsistency in its top and bottom lines for the reported periods, sudden jump in bottom line for FY26 raise eyebrows and concern over its sustainability going forward, as it is operating in a highly competitive segment. This boost appears window dressing for fancy valuations of the IPO. Its contingent liabilities stood at Rs. 7980.08 cr. as of March 31, 2026 raise big alarm.
For the last three fiscals, the company has posted an average EPS of Rs. 11.46 and an average RoNW of 22.73 %. The issue is priced at a P/BV of 4.07 based on its NAV of Rs. 75.00 (post conversion of CCDs) as of March 31, 2026, and at a P/BV of 3.03 based on its post-IPO NAV of Rs. 100.51 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 24.26. Based on FY25 earnings, the P/E stands at 80.90. The issue appears aggressively priced based on its recent average performance.
For the reported periods, PAT Margins and RoCE margins data is missing from the offer documents.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has already adopted a dividend policy in March 2025, based on its financial performance and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Oberoi Realty., Godrej Properties., Lodha Developers, Sunteck Realty, Keystone Realtors, Prestige Estate, Kalpataru Ltd., as its listed peers. They are currently trading at a P/E of 25.4, 31.1, 28.0, 19.6, 39.3, 55.9, and 45.7 (as of September 24, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The two BRLMs associated with this issue has handled 67 IPOs in the last three fiscals and out of which 19 IPOs closed below the issue price on listing date.
CONCLUSION:
REL is a real estate developer present across the full spectrum of realty development. It posted inconsistency in its financial performance for the reported periods. It ranked third in terms of new launches and sales in Mumbai. It is operating in a highly competitive segment. Based on its recent average financial data, the issue appears aggressively priced. There is no harm in skipping this pricey bet.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
