
– By Dilip Davda
- The company is engaged in providing digital commerce ecosystem consisting of data, technology, AI-driven business and promote e-commerce business for small entrepreneurs.
- The company marked consistent growth in its top lines for the reported periods.
- However, its bottom lines suffer amidst final adjustment of provision following shift in its business model.
- Following losses for the last three fiscals, the issue is priced with a negative P/E.
- However, well-informed/cash surplus investors may park funds for long term.
ABOUT COMPANY:
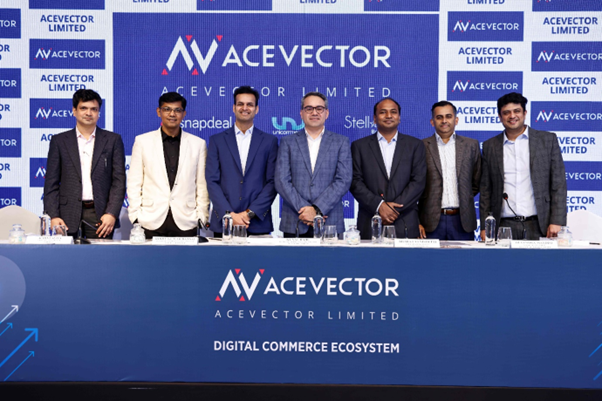
Acevector Ltd. (AL): AceVector, directly and indirectly through its Subsidiaries, operates an asset-light digital commerce ecosystem consisting of data, technology and AI-driven businesses – value e-commerce marketplace, e-commerce enablement software as a service (“SaaS”) and consumer brands. Its ecosystem includes (i) Snapdeal, a value focused lifestyle e-commerce marketplace platform with a wide selection of affordable, merchandise across lifestyle categories with an emphasis on quality; (ii) Uniware, Convertway and Shipway under the Unicommerce brand, operated by its subsidiary Unicommerce eSolutions Limited, a comprehensive suite of e-commerce enablement SaaS products, which enables end-to-end management of e-commerce operations; and (iii) Stellaro Brands business, an omnichannel value focused consumer brands retailing business, operated by its Subsidiary, Stellaro Brands Private Limited.
Together, these businesses cover the entire e-commerce value chain across B2C and B2B segments catering to multiple stakeholders vertically viz., through both online and offline modes and horizontally viz., consumers, sellers, brands and logistics providers. AceVector operates a combination of scaled and emerging platforms that generate diverse revenues from both B2C and B2B opportunities.
Snapdeal is a pure-play value marketplace (Source: 1Lattice Report), offering a wide selection of affordable, and quality curated merchandise across lifestyle categories such as fashion, home and general merchandise, and beauty and personal care, through a network of sellers offering products at value price points to the users. It serves the needs of value-conscious customers, often referred to as ‘Bharat Shoppers’. (Source: 1Lattice Report) Its vision is to be the smart, stylish, and trustworthy shopping companion offering affordable aspiration to the Indian value lifestyle shopper, where trendy merchandise meets value pricing at a good quality. The company operates Snapdeal with an asset-light, zero-inventory model, with minimal working capital risk as a true marketplace model. This operational framework, combined with the cost management strategies, particularly within its third-party logistics (3PL) supply chain, allows it to consistently deliver low prices to customers.
Snapdeal is among the top two pure-play value marketplace platforms in India in terms of revenue for Financial Year 2026, Financial Year 2025 and Financial Year 2024, which stood at Rs. 293.68 cr., Rs. 249.87 cr., and Rs. 252.89 cr., respectively (Source: 1Lattice Report). It serves customers nation-wide across 18,972 pin-codes as of the Financial Year 2026, focusing on the categories sold and the price points offered on the Snapdeal platform. The Snapdeal platform offers a shopping experience tailored for value shoppers, with value pricing, a wide assortment and a visually rich, and discovery-led user interface powered by AI driven personalization. In the Financial Year 2026, 89.83% of the transactions took place through the Snapdeal app, which is a testament to the personalized user experience it has built over the years.
The three platforms viz., Uniware, Shipway and Convertway operated by Unicommerce serve a diverse and expanded clientele with 8,261 clients, helping them streamline workflows across the pre-delivery and post-purchase stages of an order. As of March 31, 2026, its Uniware platform integrations include 151 marketplace and web-store integrations, 129 logistics partner integrations, and 11 integrations with ERP, POS, and other operational systems. In addition, its Shipway and Convertway platforms have 46 and 16 integrations, respectively, to provide flexibility to its clients for their businesses.
AceVector supports each of its businesses with tailored strategies for their organic and inorganic growth. Its businesses are further strengthened by operational synergies across technology infrastructure, supply chain capabilities, data insights and shared services, resulting in increased operational leverage. Its shared services infrastructure includes critical functions such as legal, finance, technology, corporate communications, public policy, human resources, and facilities, ensuring consistent governance and operational efficiency. It has built long-term defensibility through proprietary technologies across its businesses with deep domain expertise, bringing experienced management teams and scalable, modular infrastructure and processes.
Through its platforms, AL actively support the micro, small and medium enterprises ecosystem in India, which is an integral part of the country’s commerce and manufacturing landscape. Its sellers on the Snapdeal marketplace are largely small and medium enterprises, providing locally manufactured products tailored to the needs of value-conscious consumers. Similarly, Unicommerce’s client base also comprises small and medium enterprises, including emerging D2C brands and regional manufacturers, who rely on its automation to scale their business operations efficiently. Stellaro Brands sources its products exclusively from such local enterprises. Across its platforms, the company promotes inclusive growth by supporting local manufacturing, entrepreneurship, and women-led businesses from across the country. As of March 31, 2026, it had 332 employees on its payroll.
According to the management, with business swap, new technology, user friendly gestures, it has progressed well in the last three fiscals, and once they expand their platform and digital framework, they are confident of improving their top lines with commensurate surge in bottom lines. They posted growth in their customer base by over 55% inFY26 over FY25. It is poised for enough headroom with improving margins.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO worth Rs. 420.00 cr. (of approx. 131250000 equity shares at the upper cap). The IPO consists of fresh equity shares worth Rs. 287.00 cr. (approx. 89687500 equity shares at the upper cap) and an Offer for Sale (OFS) of 41562500 equity shares (worth Rs. 133.00 cr. at the upper cap). The company has announced a price band of Rs. 30 – Rs. 32 per equity shares of Re. 1 each. The issue opens for subscription on September 25, 2026, and will close on September 29, 2026. The minimum application to be made is for 468 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 24.12% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 132.00 cr. for funding marketing and business promotion expenses of the Marketplace business of the company, Rs. 50.00 cr. for technology infrastructure cost of the Marketplace business, and the rest for funding inorganic growth through acquisitions / general corporate purposes.
The three joint Book Running Lead Managers (BRLMs) to this issue are IIFL Capital Services Ltd., CLSA India Pvt. Ltd., Systematix Corporate Services Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Systematix Shares & Stocks (India) Ltd. is a syndicate member.
After issuing initial equity shares at par value, the company has issued/converted further equity shares in the price range of Rs. 36.00 – Rs. 63007.56 per share, (based on Re. 1 FV), between September 2009, and May 2026. The company also issued bonus shares in the ratio of 159 for 1 in December 2021. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 3.26, Rs. 3.68, Rs. 5.90, Rs. 7.30, Rs. 31.03, Rs. 40.52, Rs. 46.45, Rs. 46.49, 217.54, Rs. 382.40, Rs. 406.25, and Rs. 762.60 per share.
Post-IPO, its current paid-up equity capital of Rs. 45.45 cr. (454499270 equity shares) will stand enhanced to Rs. 54.42 cr. (544186770 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 1741.40 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit/ -(loss), of Rs. 384.74 cr. / Rs. – (51.30) cr. (FY24), Rs. 406.77 cr. / Rs. – (126.31) cr. (FY25), and Rs. 537.67 cr. / Rs. – (45.51) cr. (FY26). Despite growth in its top line, it marked see-saw in its bottom lines for the reported periods. Its P/E stands negative as it has incurred losses at the net level for all these years.
For the last three fiscals, the company has posted an average EPS of Rs. – (1.88) and an average RoNW of – (79.82) %. The issue is priced at a P/BV of 14.48 based on its NAV of Rs. 2.21 as of March 31, 2026, and at a P/BV of 4.48 based on its post-IPO NAV of Rs. 7.15 per share at the upper cap.
If we attribute FY26 earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a negative P/E, Based on FY25 earnings, the P/E stands Negative. The issue appears aggressively priced (Negative–due to losses its P/E ratio not ascertainable) based on its recent average performance.
For the reported periods, the company has not given data for PAT margins / RoCE Margins as it has posted losses for referred periods.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has already adopted a dividend policy in July 2025, based on its financial performance and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown FSN E-Commerce, Brainbees Solutions, Meesho Ltd., as its listed peers. They are currently trading at a P/E of 362.0, NA, and NA (as of September 24, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The three BRLMs associated with this issue has handled 67 IPOs in the last three fiscals and out of which 21 IPOs closed below the issue price on listing date.
CONCLUSION:
AceVector is engaged in providing digital commerce ecosystem consisting of data, technology, AI-driven business and promote e-commerce business for small entrepreneurs. The company marked consistent growth in its top lines for the reported periods. However, its bottom lines suffer amidst final adjustment of provision following shift in its business model. Following losses for the last three fiscals, the issue is priced with a negative P/E. However, well-informed/cash surplus investors may park funds for long term in this pure long term story.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
