
– By Dilip Davda
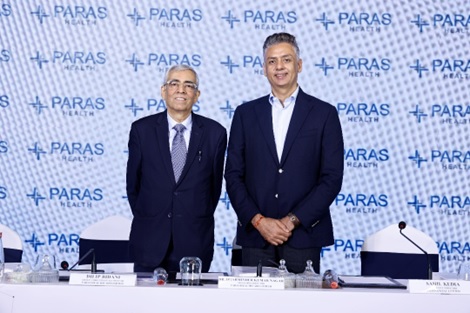
- The company is a clinical specialty-led hospital platform providing tertiary and quaternary healthcare services under its own brand “Paras Health”.
- Currently it operates with 2211 beds in its eight hospitals in Northern India, Bihar and Jharkhand.
- It has plans to increase its bed capacity to 3011 beds by FY28 end.
- The company has posted steady growth in its top lines for the reported periods, and turned the corner from FY26 onwards.
- Based on its recent average financial data, the issue appears fully priced.
- Well-informed investors may park funds for long term.
ABOUT COMPANY:
Paras Healthcare Ltd. (PHL) is a clinical specialty-led hospital platform providing tertiary and quaternary healthcare services through a network of eight hospitals with an aggregate bed capacity of 2,211 beds as of June 30, 2026 across North India, Bihar and Jharkhand. It operates under the “Paras Health” brand, with a presence in five states and one union territory – Gurugram and Panchkula in Haryana; Patna and Darbhanga in Bihar; Kanpur in Uttar Pradesh; Udaipur in Rajasthan; Ranchi in Jharkhand; and Srinagar in the union territory of Jammu and Kashmir.
The company has a committed pipeline for expansion of network, with the planned addition of a hospital with a bed capacity of 300 beds in Gurugram and a hospital with a capacity of 500 beds in Ludhiana, which it intends to launch by Fiscal 2027 and Fiscal 2028, respectively. The company expects to increase total bed capacity across hospitals to 3,011 beds by March 31, 2028. Over its 20-year operating history, it has developed specialty clusters within its hospitals through investments in advanced clinical infrastructure, skilled medical talent and standardized care protocols. Its hospitals are designed to deliver high-acuity care and offer treatments across a broad spectrum of clinical specialties, with a deep focus on cardiac sciences, oncology sciences, neuro sciences, gastro sciences, orthopedics and sports injury, and renal sciences (collectively, “CONGOR”). These CONGOR specialties accounted for 74.35%, 75.30%, 74.70%, 71.92% and 72.34% of its revenue from operations in the three months period ended June 30, 2026 and June 30, 2025, and Fiscals 2026, 2025 and 2024, respectively. As of June 30, 2026, it had 1,084 doctors and 1,937 nurses across its hospital network.
Over the three months period ended June 30, 2026 and the last three Fiscals, on a consolidated basis, PHL has demonstrated strong growth driven by an increase in patient volumes across hospitals. Its revenue from operations has grown at a CAGR of 19.26% from Rs. 1129.04 cr. in Fiscal 2024 to Rs. 1605.95 cr. in Fiscal 2026, driven by an increase in Occupied Bed Days and ARPOB at its Mature Hospitals, reflecting continued focus on high-acuity specialties and clinical programs. Its EBITDA has grown at a CAGR of 47.41% from Rs. 154.41 cr. in Fiscal 2024 to Rs. 335.58 cr. in Fiscal 2026, with EBITDA margins expanding as its Emerging Hospitals and New Hospitals have begun to ramp up, generating operating leverage. Its revenue from operations increased by 27.66% from Rs. 368.39 cr. in the three months period ended June 30, 2025 to Rs. 470.28 cr. in the three months period ended June 30, 2026, and its EBITDA increased by 71.13% from Rs. 66.31 cr. in the three months period ended June 30, 2025 to Rs. 113.48 cr. in the three months period ended June 30, 2026.
It established its first hospital in Gurugram, Haryana in 2006 with 200 beds, making it the first corporate hospital entrant among listed peers in the city. (Source: CRISIL Report) Over the years, it has expanded hospital platform in a largely organic manner, focusing on operationalizing and scaling hospitals through internal accruals and debt financing, with limited equity infusions. It has increased its total bed capacity from 2,135 beds as of March 31, 2024 to 2,211 beds as of June 30, 2026, and is one of the largest healthcare providers in North India, Bihar and Jharkhand in terms of bed capacity as of June 30, 2026. (Source: CRISIL Report).
It has consistently identified underserved markets with large catchment populations where it believes there is a need for high-quality tertiary and quaternary care, strong demand for healthcare services, as well as proximity to medical colleges to source medical professionals; and have set up hospitals in these locations.
PHL’s eight hospitals are at different stages of operational maturity, which correlates to their occupancy levels, margins and growth trajectories. This balanced mix of mature, emerging and New Hospitals enables it to combine stable cash generation with visible growth headroom, and has supported consolidated margin expansion over time as newer hospitals increase their occupancy levels.
The company operates its hospitals through a mix of owned, leased, revenue-sharing and public-private partnership models, and has adopted a calibrated approach to capital deployment, evaluating capital-efficient structures selectively based on market characteristics, capital efficiency considerations and long-term operating control. Its leased facilities are structured through fixed rent, revenue sharing or hybrid arrangements comprising a partial fixed rent and a partial revenue share. Company’s growth decisions are guided by defined return thresholds and the strength of its balance sheet.
PHL has gradually expanded its presence across North India, Bihar and Jharkhand, growing its bed capacity from 200 beds as of June 2006 to 2,211 beds as of June 30, 2026, while simultaneously deepening specialty programs and improving operating metrics as hospitals mature. The company has planned a total bed capacity of 3011 by the end of FY28. The ‘Paras Health’ brand is well-recognized for its commitment to clinical excellence, accessibility and patient-centric care, as reflected in its patient satisfaction score of 90.60 as of March 31, 2026, as well as its net promoter score of 93.31 as of the same date. Together, these metrics demonstrate consistent patient satisfaction across its hospital network. PHL’s focus on quality is further reinforced by seven of its eight hospitals being accredited by the NABH. Further, with effect from May 21, 2026, it has become an executive member of the Association of Healthcare Providers (India). It has also been recently certified as a ‘Great Place to Work’ in India, which reflects its focus on fostering a positive workplace culture. As of June 30, 2026, it had a team of 5,315 professionals, including 1,084 doctors, 1,937 nurses and 2,294 other personnel. Its doctors are engaged on a payroll basis, on a full-time or part-time consultancy basis.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO worth Rs. 1450 cr. (approx. of 20923521 equity shares at the upper cap). The IPO consists of fresh equity shares worth Rs. 500 cr. (approx. 7215007 equity shares at the upper cap), and an Offer for Sale (OFS) worth Rs. 950 cr. (approx. 13708514 equity shares at the upper cap). The company has announced a price band of Rs. 660 – Rs. 693 per equity shares of Re. 1 each. The issue opens for subscription on October 21, 2026, and will close on October 23, 2026. The minimum application to be made is for 21 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 19.34% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity shares issue, the company will utilize Rs. 320.90 cr. for repayment/prepayment of certain borrowings, Rs. 54.10 cr. for investment in its wholly owned subsidiary PMHPL for repayment/prepayment of its certain borrowings, and the rest for general corporate purposes.
The company has allocated not less than 75% for QIBs, not more than 15% for HNIs, and not more than 10% for Retail investors.
The joint Book Running Lead Managers (BRLMs) to this issue are JM Financial Ltd., BofA Securities India Ltd., Nuvama Wealth Management Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. JM Financial Services Ltd., Nuvama Wealth Management Ltd. are the syndicate members.
Having issued initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 3.50 – Rs. 237 per share (based on Re. 1 FV), between February 2006, and April 2025. It has also issued bonus shares in the ratio of 1 for 1 in March 2024. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 2.35, and Rs. 114.15 per share.
Post-IPO, its current paid-up equity capital of Rs. 10.10 cr. (100986187 equity shares) will stand enhanced to Rs. 10.82cr. (108201194 equity shares) at the upper cap. Based on the upper band, the company is looking for a market cap of Rs. 7498.34cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit/ – (loss), of Rs. 1151.02 cr. / Rs. – (15.33) cr. (FY24), Rs. 1314.21 cr. / Rs. – (57.98) cr. (FY25), and Rs. 1628.78 cr. / Rs. 43.83 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 49.68 cr. on a total income of Rs. 478.45 cr. The company posted growth in its top lines for the reported periods, and reported turnaround from FY26 onwards. Rising trade receivables year-on-year raise concern. Its contingent liabilities stood at Rs. 398.44 cr. as of June 30, 2026. Its debt equity ratio was at 3.21 as of June 30, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. – (0.07) and an average RoNW of – (1.14) %. The issue is priced at a P/BV of 15.73 based on its NAV of Rs. 44.06 as of June 30, 2026, and at a P/BV of 8.38 on the basis of post-IPO NAV of Rs. 82.71 per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 37.72. Based on FY26 earnings, the P/E stands at 171.11. The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of – (1.33) % (FY24), – (4.41) % (FY25), 2.69% (FY26), 10.38% (Q1-FY27), and RoCE margins of 5.86%, 2.71%, 10.76%, 4.23%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has adopted a dividend policy in July 2024, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Aster DM, Apollo Hospitals, Fortis Healthcare, Global Health, Jupiter Lifeline, Krishna Institute, Manipal Health, Max Healthcare, Narayana Hrudayalaya, and Yatharth Hospital, as its listed peers. They are currently trading at a P/E of 163.0, 53.7, 52.4, 58.2, 43.0, 138.0, 96.2, 55.0, 40.8, and 52.7 (as of October 16 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The three BRLMs associated with this issue have handled 83 public issues in the past three fiscals, out of which 25 issues closed below the offer price on listing date.
CONCLUSION:
PHL is a clinical specialty-led hospital platform providing tertiary and quaternary healthcare services under its own brand “Paras Health”. Currently it operates with 2211 beds in its eight hospitals in Northern India, Bihar and Jharkhand. It has plans to increase its bed capacity to 3011 beds by FY28 end. It has one hospital in Kashmir J & K Union Territory as well. The company has posted steady growth in its top lines for the reported periods, and turned the corner from FY26 onwards. Based on its recent average financial data, the issue appears fully priced. Well-informed investors may park funds for long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
