
– By Dilip Davda
- The company is one of the leading alternatives platforms in India on the basis of its AUM.
- The company posted growth in its top and bottom lines for the reported periods.
- Its performance always remains linked to market related risks.
- Based on its recent average financial data, the issue appears aggressively priced.
- Only well-informed investors may park moderate funds for long term.
ABOUT COMPANY:
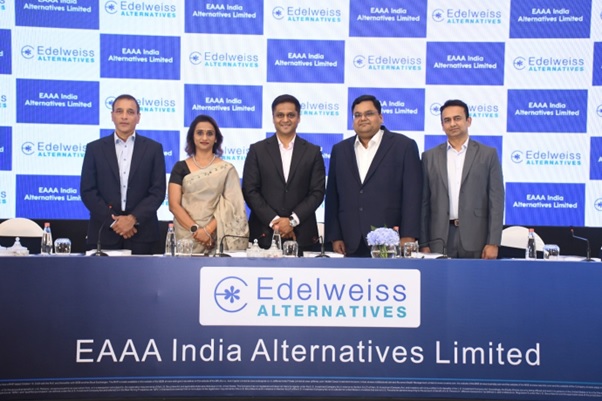
EAAA India Alternatives Ltd. (EIAL) is one of the leading alternatives platforms in India, in terms of assets under management (“AUM”) with more than 17 years of experience (Source: CARE Report) of managing long term patient capital with an AUM of Rs. 95344.88 cr., as of June 30, 2026. Its key business verticals include: (i) real assets (“Real Assets”), which invests in a mix of equity, quasi-equity and debt instruments and (ii) private credit (“Private Credit”), which primarily invests in debt or convertible debt instruments and secular instruments for superior risk adjusted returns.
Its wholly owned subsidiary, Sekura India Management Limited (“Sekura”), is part of its — asset operating and management team and proficiently supports its various business verticals, including operations, maintenance, monitoring, efficiency improvement, and turnaround management. It is an experienced player, catering to a diverse client base of global and domestic institutional clients and manage India focused funds across its business verticals. As of June 30, 2026, EIAL’s FPAUM totaled Rs. 48623.18 cr. Over last three financial years, its FPAUM grew at compounded annual growth rate (“CAGR”) of approximately 23.43% to Rs. 44710.44 cr. In FY26. Most of its large funds are in or entering in their third and fourth series, and it has consistently been able to raise capital across the series, indicating its ability to generate sustainable performance, maintain client confidence, and adapt to market conditions.
In the last three fiscals and the three months period ended June 30, 2026, it raised capital commitment aggregating to Rs. 47526.25 cr., deployed investments aggregating to Rs. 38229.40 cr. and realized investments aggregating to Rs. 31232.94 cr. Most of its funds also have a track record of delivering strong performance consistently across different market cycles. Such strong realizations of its funds ensured the return of realized portion of NAV back to clients, thereby establishing a track record of delivering strong performance. It has invested significant time and resources over the years in building a global, scalable, coverage platform for a diverse client base including institutional investors, ultra-high net worth individuals (“UHNIs”), high net worth individuals (“HNIs”) and family offices. As of June
30, 2026, through the funds that it managed, EIAL has 11009 client relationships globally and in India, including 1493 repeat clients (i.e., clients who have invested in more than one of its funds) and 8,800 clients added from April 1, 2023 to June 30, 2026. As of June 30, 2026, 77% of its AUM comprised of commitments made by its repeat clients, signifying the strength of its long-standing client relationships.
This high percentage underscores the trust and confidence that its clients have in company’s platform and investment strategies, as well as its consistent ability to deliver performance and maintain client satisfaction over time. EIAL has a diverse client base; approximately 49.32% of its AUM is contributed by institutional clients as of June 30, 2026, including pension funds, insurance companies, banks etc., while the remaining 50.68% is contributed by non-institutional clients (including UHNIs/HNIs and family offices, corporate and others etc.). Additionally, as of June 30, 2026, its client base extends to multiple geographies globally including India, North America and Europe. Its presence in Mumbai, New Delhi, GIFT City and Singapore ensures on ground coverage through its chaperoning partners and
relationship managers, covering North America, Europe, Middle East, Japan, Australia and South Korea. This also offers it flexibility to create solutions for both onshore and offshore clientele. Out of the cumulative Variable Additional Return of Rs. 684.72 cr. recognized by the Company from Financial Year 2024 up to the three-month period ended 30 June 2026, an amount of Rs. 397.65 cr. has been realized. As of June 30, 2026, it had overall 277 employees on its payroll.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route secondary IPO worth Rs. 1200 cr. (approx. 7207207 equity shares at the upper cap). The company has announced a price band of Rs. 1585 – Rs. 1665 per equity shares of Rs. 5 each. The issue opens for subscription on October 26, 2026, and will close on October 28, 2026. The minimum application to be made is for 9 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 11.15% of the post-IPO paid-up equity capital. This being a pure Offer for Sale (OFS), no funds are going to company. The issue is being made to provide exit to some of its stakeholders, and unlock the listing benefits.
The joint Book Running Lead Managers (BRLMs) to this issue are Axis Capital Ltd., Jefferies India Pvt. Ltd., Motilal Oswal Investment Advisors Ltd., and Nuvama Wealth Management Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Motilal Oswal Financial Services Ltd., Nuvama Wealth Management Ltd. Are syndicate members.
Having issued initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 25 – Rs. 933 per share (based don Rs. 5 FV) between December 2008, and September 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. NA, Rs. 51.84, Rs. 85.00, and Rs. 86.50 per share.
Post-IPO, its current paid-up equity capital of Rs. 32.33 cr. (64655246 equity shares) will stand same as this is a hundred percent secondary issue. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 10765.10 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 584.252 cr. / Rs. 175.16 cr. (FY24), Rs. 786.54 cr. / Rs. 229.78 cr. (FY25), and Rs. 963.76 cr. / Rs. 265.20 cr. (FY26). For Q1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 80.71 cr. on a total income of Rs. 336.13 cr. The company posted growth in its performances for the reported periods. Its trade receivables stood at Rs. 154.46 cr. As of June 30, 2026 against Rs. 166.90 as of March 31, 2026, that raise concern. Its contingent liabilities stood at Rs. 37.70 cr. as of June 30, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 37.09 (basic) and an average RoNW of 26.57 %. The issue is priced at a P/BV of 9.42 based on its NAV of Rs. 176.67 as of June 30, 2026, as well as on the basis of post-IPO NAV per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 33.35. Based on FY26 earnings, the P/E stands at 40.59. The issue appears aggressively priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 29.98% (FY24), 29.21% (FY25), 27.52% (FY26), 24.01% (Q1-FY27), and RoE margins of 27.30%, 27.10%, 25.97%, 28.96%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has paid a dividend of 640% (FY26), and 190% (till the date of this prospectus – for FY27). It has adopted a dividend policy in January 2026, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown 360 ONE WAM, ABSL AMC, Anand Rathi Wealth, HDFC AMC, Gaja Alternative Asset, Nippon Life India AMC, Nuvama Wealth, UTI AMC, ICICI Prudential AMC, as its listed peers. They are currently trading at a P/E of 32.6, 26.6, 81.6, 32.3, 18.9, 35.2, 28.4, 20.0, and 37.1 (as of October 23, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The four BRLMs associated with this issue have handled 114 public issues in the past three fiscals, out of which 30 issues closed below the offer price on listing date.
CONCLUSION:
EIAL is one of the leading alternatives platforms in India on the basis of its AUM. The company posted growth in its top and bottom lines for the reported periods. Its performance always remains linked to market related risks. Recent AMC and AIF funds segment primary offers have fared poorly amidst sliding market sentiments. Based on its recent average financial data, the issue appears aggressively priced. Only well-informed investors may park moderate funds for long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
