
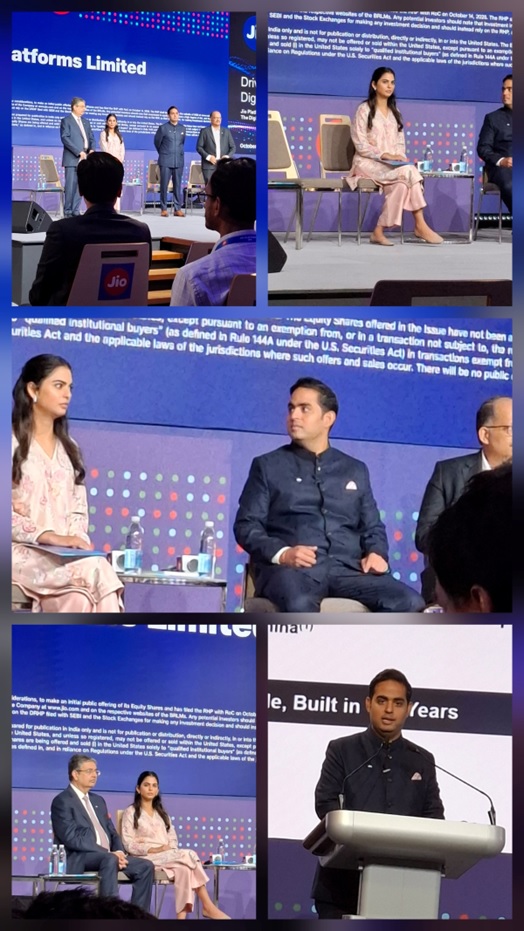
– By Dilip Davda
- The company is a well-diversified technology platform providing telecom, IT, and AI embedded products and related services.
- The company continues its leadership in this segment, and is poised for more bright prospects ahead.
- It posted steady growth in its top and bottom lines for the reported periods.
- Though prima-facie it appears fully priced, considering its plans afoot, its offer appears reasonably priced.
- The company is diluting just around 3% equity and will turn debt-free, resultantly, its bottom lines will improve.
- Investors across the board can park funds for medium to long term.
ABOUT COMPANY:
Jio Platforms Ltd. (JPL) is a technology platform, built on proprietary digital technology and pan-India digital connectivity as the foundational layer, driving digital transformation in India. Since its inception, the company has played a pivotal role in democratizing access to digital connectivity and digital services in India. Jio Platforms’ digital connectivity forms one of the fundamental pillars of India’s growing digital economy, which is expected to reach $1.4 trillion (Rs. 125.8 trillion) by Fiscal 2031, as per the Analysys Mason Report. Its Subsidiary, Reliance Jio Infocomm Limited (“RJIL”), served 533.3 million customers in India, as of June 30, 2026. A combination of mobile, fixed broadband and digital services across a unified platform, together with data and customer personalization, positions JPL as a comprehensive digital gateway for accessing the internet, digital services and emerging technologies, including artificial intelligence (“AI”).
Company’s business model is built on a proprietary technology stack that it has designed, developed and deployed in-house. It has vertically integrated technology capabilities across network, device engineering, software and operating systems, and digital applications. This full-stack ownership helps it to significantly reduce dependency on third-party vendors, provides structural cost advantages, and enables faster innovation cycles. As of June 30, 2026, the Company had 12,477 employees in the digital products and technology development team, representing approximately 45% of its total full-time employees. Of these 12,477 employees, 8,156 are involved in the development of digital products and services while the remaining are engaged in network technology engineering. As of June 30, 2026, the Company and its Subsidiaries have applied for 7,220 patents, across 4G, 5G, 6G cloud-native core network architectures, AI-driven network automation, and other digital technologies within India (2655) and outside India (4565). The Company was ranked among the top 20 global companies in the Patent Cooperation Treaty rankings in 2025, according to the World Intellectual Property Organisation. It believes this depth of proprietary technology provides it with a competitive advantage and positions as a technology platform that uses connectivity as its foundational core distribution layer. Further, by leveraging this proprietary technology stack, the company is transitioning into an AI-native digital services company endeavoring to deliver connected intelligence and agentic AI services at scale to consumers and businesses.
In modern software-driven network architecture, the traditional distinction between ‘telecom’ and ‘technology’ no longer applies. Its position is more grounded in technology, given that it has designed, built, and deployed entire network and services stack primarily using proprietary technology, from radio access network to core capabilities, from operating systems to digital applications. Technology is the fundamental architecture of how its business is structured, built, and operated.
JPL is the only digital connectivity provider globally with an end-to-end, proprietary 5G standalone (“SA”) technology stack, as per the Analysys Mason Report. It has in-house hardware and software capabilities – evidenced through the design of its set-top-box and the JioBharat OS, which can operate on low-cost chipsets and with minimal memory footprint, enabling high quality digital services on affordable devices.
JioBrain, its proprietary AI engine, is embedded across network operations enabling autonomous decision making for capacity allocation, fault prediction, and real-time network optimization. JioAirFiber scaled to 14.0 million customers as of June 30, 2026, from the time of its launch in September 2023 – making it the largest fixed wireless customer base in India – enabled by its proprietary UBR-based fixed wireless access (“FWA”) technology, as per the Analysys Mason Report.
In 4G, it was the first to roll out an all-IP, greenfield 4G LTE network at scale and achieved 100 million customers in less than six months as per the Analysys Mason Report, and in 5G, JPL achieved the fastest rollout globally with pan-India coverage in 15 months and 284.9 million customers in 45 months as per the Analysys Mason Report.
JPL is progressively embedding AI across its technology stack and offerings to achieve Level 4 on the TM Forum’s Autonomous Networks scale, where networks operate, maintains and evolves end-to-end autonomously, and offer AI-assisted services to customers. Its nation-scale phygital reach supports rapid delivery of digital services to customer base and drives swift adoption. Since its launch in 2016, the company has followed a deliberate strategy of offering a wide suite of digital services with digital connectivity as an enabler of seamless access to digital services. Certain aspects of its platform have been developed through partnerships with suppliers, and it has also built partnerships with third-parties for cloud infrastructure, content and AI features, which are non-exclusive and subject to renewal.
JPL launched 4G network with 4G voice over LTE (“VoLTE”) technology in 2016 and were amongst the first few greenfield all-internet protocol operators globally to launch 4G voice on this technology. India is one of the fastest adopters of 5G globally and it is the first operator in India to launch a standalone 5G network, with 284.9 million 5G subscribers as of June 30, 2026. The company launched its 5G offering in October 2022, and achieved a record rollout, deploying more than one million 5G cells within one year. As of March 31, 2026, its 5G customer base was the third largest in the world. (Source: Analysys Mason Report).
To support the 5G rollout, it developed a “Made in India”, end-to-end 5G technology stack with its own portfolio of 4G+5G combination core, 5G devices and OSS and BSS operating systems, as per the Analysys Mason Report. Built on a modern, software-defined architecture with extensive automation and in-house orchestration platforms, this stack supports rapid design, testing and nationwide rollout at scale. With this capability, JPL helped India become only the fifth country globally to possess such indigenous 5G capability, as per the Analysys Mason Report.
Thus, the company has on its platter more services and offerings beyond mobile connectivity and data network. It has well diversified business model across its offerings which will make it a global Indian player in telecom, IT, and AI embedded most modern services.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route IPO of 270000000 equity shares worth Rs. 30213 cr. at the upper cap. The company has announced a price band of Rs. 1065 – Rs. 1119 per equity shares of Rs. 10 each. The issue opens for subscription on October 21, 2026, and will close on October 23, 2026. The minimum application to be made is for 12 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 2.93% of the post-IPO paid-up equity capital. From the net proceeds of the IPO, the company will utilize Rs. 27500 cr. for repayment/prepayment of certain borrowings availed by its material subsidiary RJIL, and the rest for general corporate purposes.
The company has reserved shares worth Rs. 500 cr. (approx. 4468275 equity shares at the upper cap) for its eligible employees, and offering them a discount of Rs. 54 per share. It has also reserved shares worth Rs. 2500 cr. (approx. 22341376 equity shares) for the shareholders of RIL. From the rest, it has allocated not more than 50% for QIBs, not less than 15% for HNIs, and not less than 35% for Retail investors.
The 19 joint Book Running Lead Managers (BRLMs) to this issue are Kotak Mahindra Capital Co. Ltd., Morgan Stanley India Company Pvt. Ltd., BofA Securities India Ltd., Axis Capital Ltd., BNP Paribas, Citigroup Global Markets India Pvt. Ltd., CLSA India Pvt. Ltd., DAM Capital Advisors Ltd., Goldman Sachs (India) Securities Pvt. Ltd., HDFC Bank Ltd., HSBC Securities and capital Markets (India) Pvt. Ltd., ICICI Securities Ltd., IIFL Capital Services Ltd., Jefferies India Pvt. Ltd., JM Financial Ltd., J.P. Morgan India Pvt. Ltd. , SBI Capital Markets Ltd., UBS Securities India Pvt. Ltd., and 360 ONE WAM Ltd., while KFin Technologies Ltd. is the registrar to the issue. HDFC Securities Ltd., Investec Capital Services (India) Pvt. Ltd., JM Financial Services Ltd., Kotak Securities Ltd., SBICAP Securities Ltd., Sharekhan Ltd., 360 ONE Capital Market Pvt. Ltd., 360 ONE Distribution Services Ltd. as syndicate members.
Having issued initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 488.34 – Rs. 549.31, per share between July 2020, and Deccember2020. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 89.58 per share.
Post-IPO, its current paid-up equity capital of Rs. 8939.03 cr. (8939030830 equity shares) will stand enhanced to Rs. 9209.03 cr. (9209030830 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 1030491 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 110175.40 cr. / Rs. 21434.00 cr. (FY24), Rs. 129333.00 cr. / Rs. 26120.30 cr. (FY25), and Rs. 149759.10 cr. / Rs. 30052.70 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 7764.10 cr. on a total income of Rs. 40197.90 cr. The company posted growth in its performances for the reported periods. Its trade receivables are rising year-on-year. Its contingent liabilities stood at Rs. 343247.30 cr. as of June 30, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 30.55 (basic) and an average RoNW of 9.04 %. The issue is priced at a P/BV of 2.93 based on its NAV of Rs. 382.34 as of June 30, 2026, and at a P/BV of 2.77 on the basis of post-IPO NAV of Rs. 403.91 per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 33.19. Based on FY26 earnings, the P/E stands at 34.29 The issue appears fully priced based on its recent average performance. But considering its OTT play and other advanced technology of AI, it is poised to be a global Indian player in the segment, making it reasonably priced.
For the reported periods, the company has reported PAT Margins of 19.55% (FY24), 20.36% (FY25), 20.46% (FY26), 19.82% (Q1-FY27), and RoCE margins of 12.83%, 12.50%, 10.76%, 2.56%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has adopted a dividend policy in April 2026, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Bharti Airtel, Vodafone Idea, as its listed peers. They are currently trading at a P/E of 37.0 and NA (as of October 15, 2026). However, they are not truly comparable on an apple-to-apple basis.
MERCHANT BANKER’S TRACK RECORD:
The nineteen BRLMs associated with this issue have handled 160 public issues in the past three fiscals, out of which 46 issues closed below the offer price on listing date.
CONCLUSION:
JPL is a well-diversified technology platform providing telecom, IT, and AI embedded products and related services. The company continues its leadership in this segment, and is poised for more bright prospects ahead. It posted steady growth in its top and bottom lines for the reported periods. Though prima-facie it appears fully priced, considering its plans afoot, its offer appears reasonably priced. The company is diluting just around 3% equity and will turn debt-free, resultantly, its bottom lines will improve. The second generation entrepreneurs are confident of maintaining the RIL group’s legacy of rewarding stakeholders. Investors across the board can park funds for medium to long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
