
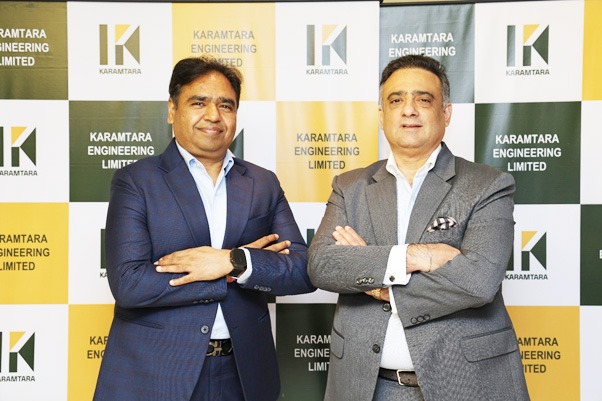
– By Dilip Davda
- The company is a backward integrated manufacturer of renewable energy and transmission line sector products.
- It supplies it products to domestic as well as international markets, being the largest integrated manufacturer in terms of installed capacity in India.
- The company is operating in a highly competitive and crowded segment.
- Based on its recent average financial data, the issue appears aggressively priced.
- Well-informed/cash surplus investors may park funds for medium to long term.
ABOUT COMPANY:
Karamtara Engineering Ltd. (KEL) is a backward integrated manufacturer of products for renewable energy and transmission lines sectors. It is the largest integrated manufacturer in terms of installed capacity in India for solar mounting structures and tracker components in Fiscal 2026 according to the F&S Report. Its aggregate installed capacity was 889200 MTPA (including 492000 MTPA for solar products equivalent to approximately 16.81 GW) and 480000 pieces as of March 31, 2026 (excluding its galvanizing capacity). The company offers a diverse product portfolio which enables it to serve as a one-stop shop for solar structures (fixed-tilt and trackers). The company offers structures and fasteners in the solar energy and transmission sectors, and overhead transmission line (“OHTL”) hardware fittings and accessories.
It is one of the largest exporters of solar products from India to North America in Fiscal 2025 (Source: F&S Report). It has also forayed into the wind energy sector by commencing production of angular towers for wind turbines and tubular towers for wind turbines in March 2025 and June 2025, respectively. Further, KEL intends to enter into the business of battery energy storage systems (“BESS”) through its wholly owned subsidiary (being Karamtara Green Energy Limited (“KGEL”)) that was incorporated in May 2025. In addition, it intends to set up manufacturing facilities for prefabricated engineered building (“PEB”) structures. It has a wide geographical footprint with a global delivery model, with exports to over 50 countries cumulatively as of March 31, 2026, across North America, Europe, Asia, Africa, Australia and Latin America. It has built a strong customer base of international customers, including original equipment manufacturers (“OEMs”) and engineering, procurement and construction (“EPC”) companies and independent power producers (“IPPs”).
According to the F&S Report, KEL serves 16 of the top 24 EPC companies in the United States (in terms of installed capacity totaling to approximately 233 GW) as of March 31, 2026. Its revenue from exports grew at a CAGR of 11.89% from Rs. 1395.83 cr. in Fiscal 2024 to Rs. 1747.49 cr. in Fiscal 2026, representing 57.56% and 40.52% of its total revenue from operations during the corresponding years, respectively.
The company is recognized as a Four Star Export House by the Directorate General of Foreign Trade, Ministry of Commerce & Industry, Government of India, establishing its contribution to foreign trade.
According to the F&S Report, it is one of the largest players in India in terms of number of product offerings in the solar sector as of March 31, 2026. Its extensive product portfolio includes structures in the solar energy sector (such as solar module mounting structures (“Solar MMS”), solar tracker piles and piers and solar torque tubes) and the transmission sector (such as lattice towers for transmission line). Further, it has commenced production of angular towers for wind turbines and tubular towers for wind turbines in March 2025 and June 2025, respectively.
In addition, the company manufactures fasteners (such as bolts, nuts, studs and washers), structural steel profiles (such as angles, channels and beams) and OHTL hardware fittings and accessories (such as insulator string fittings, jumper tubes, suspension clamps and vibration dampers). KEL operated 13 manufacturing facilities in India and internationally, as of March 31, 2026. Eight manufacturing facilities were located in Maharashtra, India, four manufacturing facilities in Gujarat, India and one manufacturing facility was in Italy as of the same date. It places key focus on backward integration capabilities. It is one of the few product manufacturers to operate in-house galvanizing facilities, which is also the largest installed capacity in the solar energy sector in India with a capacity of 276800 MTPA as of March 31, 2026 (Source: F&S Report).
The company also has two in-house rolling mill furnaces to manufacture various grades of structural steel for a wide range of products, including angles, channels and beams used across the solar energy and transmission industries. These in-house facilities provide it with significant competitive advantages in manufacturing processes, including supply chain advantages, time efficiency and cost benefits. As of March 31, 2026, it had 1015 employees on its payroll, and additional 560 contractual workers.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO worth Rs. 875 cr. (of approx. 34448819 equity shares at the upper cap). The IPO consists of fresh equity shares worth Rs. 675 cr. (approx. 26574803 equity shares at the upper cap) and an Offer for Sale (OFS) worth Rs. 200 cr. (of 7874016 equity shares at the upper cap). The company has announced a price band of Rs. 241 – Rs. 254 per equity shares of Rs. 10 each. The issue opens for subscription on September 09, 2026, and will close on September 11, 2026. The minimum application to be made is for 59 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 10.70% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 600.00 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes.
The joint Book Running Lead Managers (BRLMs) to this issue are JM Financial Ltd., ICICI Securities Ltd., and IIFL Capital Services Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. JM Financial Services Ltd. is a syndicate member.
After issuing initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 310.00 – Rs. 400.00 per share (on the basis of Rs. 10 FV), between September 2013, and January 2025. It has also issued bonus shares in the ratio of 5 for 1 in March 2007, 7 for 3 in March 2009, 50 for 1 in December 2024. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. NIL per share.
Post-IPO, its current paid-up equity capital of Rs. 295.25 cr. (295247996 equity shares) will stand enhanced to Rs. 321.82 cr. (321822799 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 8174.30 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 2427.12 cr. / Rs. 102.65 cr. (FY24), Rs. 3165.36 cr. / Rs. 139.33 cr. (FY25), and Rs. 4316.36 cr. / Rs. 228.75 cr. (FY26). The company posted steady growth in its top and bottom lines for the reported periods, indicating the prospects ahead. Its contingent liability stood at Rs. 116.25 cr. as of March 31, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 6.16 and an average RoNW of 19.85 %. The issue is priced at a P/BV of 6.09 based on its NAV of Rs. 41.72 as of March 31, 2026, and at a P/BV of 4.15 based on its post-IPO NAV of Rs. 61.20 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 35.72. Based on FY25 earnings, the P/E stands at 58.66. The issue appears aggressively priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 4.23% (FY24), 4.40% (FY25), 5.30% (FY26), and RoCE margins of 24.15%, 23.30%, 23.27%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has paid a dividend of 422.22% for FY25, and 5% for the period of April 01, 2026 till the date of this RHP. It has already adopted a dividend policy in January 2025, based on its financial performance and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Inox Wind, Waaree Energies, KP Green, Suzlon Energy, Premier Energies, Vikram solar, Saatvik Green, Emmvee Photovoltaic, as its listed peers. They are currently trading at a P/E of 37.3, 18.8, 10.6, 19.7, 27.3, 16.9, 21.7, and 17.7 (as of September 04, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The three BRLMs associated with this issue has handled 108 IPOs in the last three fiscals and out of which 30 IPOs closed below the issue price on listing date.
CONCLUSION:
KEL is a backward integrated manufacturer of renewable energy and transmission line sector products. It supplies it products to domestic as well as international markets, being the largest integrated manufacturer in terms of installed capacity in India. The company is operating in a highly competitive and crowded segment. Based on its recent average financial data, the issue appears aggressively priced. Well-informed/cash surplus investors may park funds for medium to long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
