
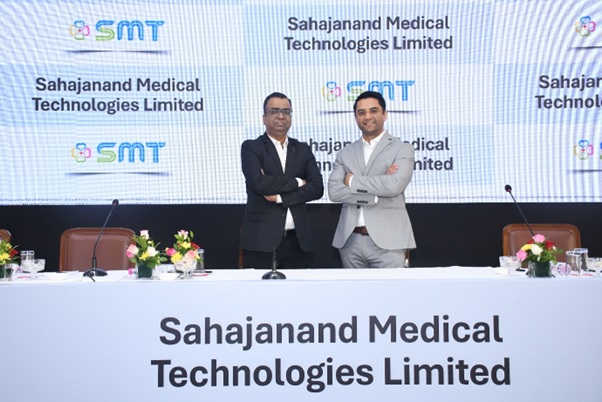
– By Dilip Davda
- The company is engaged in manufacturing medical devices across vascular and structural heart intervention.
- Its products are well established and widely accepted world over, thus enjoys prime status as a first company in the world to receive a CE certification for DES.
- Because of product shift and other provisioning, it marked losses for FY24.
- With improved products in place and expanding its capacities, it is poised for better prospects ahead.
- Based on its recent average financial data, the issue appears aggressively priced.
- However, well-informed investors may park funds for long term.
PREFACE:
The company originally filed its first draft offer documents with regulator in September 2021, for an IPO worth Rs. 1500 cr. (Rs. 410.33 cr. worth fresh equity shares and Rs. 1089.67 cr. worth offer for sale, but due to world disturbance in the form of Russia-Ukrain war, it withdrew the issue and refiled its revised draft offer document for OFS of 27644231 equity shares and as per RHP of October 2026, its final offer got reduced to 13822116 equity shares. Thus, its offer got reduced to less than one-third i.e., Rs. 478 cr.
ABOUT COMPANY:
Sahajanand Medical Technologies Ltd. (SMTL) is a Class III53 and Class C/D54 medical devices company with a portfolio of technologically advanced medical devices across vascular and structural heart intervention. According to the F&S Report, it was the first company in the world to receive a CE certification for a DES with a biodegradable polymer- based paclitaxel-eluting stent (Infinium). Over the years, it has introduced several innovative products, driven by its focus on research and development and precision manufacturing capabilities enabling it to deliver quality products backed by clinical data, with a presence across 65 countries (including India) in the three months ended June 30, 2026 and 77 countries (including India) in Fiscal 2026.
SMRL is a R&D-driven company engaged in the development of Class III and Class C/D medical devices, with an emphasis on Vascular Intervention (“VI”) and Structural Heart (“SH”). Its portfolio of (i) VI products includes coronary intervention products such as coronary stents and coronary balloons, (ii) SH products include TAVI and Occluders, and (iii) Others including its own brand of renal stents, peripheral DCBs and other trading products.
According to the F&S Report, it has a leading market share in the drug eluting stents (“DES”) market in India, with a market share of nearly 25.00% in Fiscal 2026 of the total DES sales volume in India. Further, according to the F&S Report, the company is among the top five companies in terms of market share by sales volume of DES in each of Germany, Spain, Poland and Brazil, as of March 31, 2026. Additionally, it is among the top five companies in terms of market share by sales volume of Occluders in Thailand, South Korea and India, as of March 31, 2026.
Its strategy centers on continuous innovation, expanding its product portfolio, enhancing existing products, and exploring new technologies to address evolving clinical and market needs. As of June 30, 2026, it has two R&D centers – one in India and another in Thailand, supported by a team of 156 professionals (including four consultants), each with experience in biomedical engineering, technology development, and clinical research. Additionally, it has built a robust intellectual property portfolio, with 119 patents granted globally, 78 more patent applications in the pipeline, and five design registrations in India as of the date of this Red Herring Prospectus. Its R&D focuses on expanding indications for existing products, product and process enhancements, development of new capabilities and technologies, clinical trials for new market entry, and the development of new devices.
Consequently, SMTL’s R&D efforts has resulted in an industry first and product enhancements. For instance, according to the F&S Report, it is the first company in the world to receive CE certification for an in-house developed biodegradable polymer-based paclitaxel-eluting stent (Infinium) in December 2005. It further innovated by introducing its proprietary LDZ link, which enhanced the deliverability of Supraflex Cruz (its biodegradable polymer-based DES), making it the most deliverable stent in its class according to the F&S Report. The company has also enhanced the crossing capability of its balloon catheters. Additionally, it has developed a patented AVDC system for Hydra TAVI, improving deliverability, after the acquisition of Vascular Innovations. The next generation of AVDC received CE approval in Fiscal 2026.
The company has built a strong clinical foundation for its flagship products – Supraflex Cruz, Hydra, Sironity Drug-coated PTCA Balloon, Pipit and Cocoon, supported by 75 clinical studies (comprising 66 completed studies and 09 ongoing studies), as of June 30, 2026, across diverse geographies and patient populations. SMTL’s commitment to quality is reflected in its distinction as one of the few Indian MedTech companies with results of key clinical trials on products published in top-tier journals such as The Lancet (impact factor55 109) and NEJM (impact factor 84.5), according to the F&S Report. Further, Supraflex Cruz has been shown to offer better deliverability and clinical outcomes than the DES of leading competitors, while Hydra and Cocoon stand out among peers for their advanced features and safety profiles, according to the F&S Report.
The company marketed its products in 77 countries (including India) in Fiscal 2026, through a mix of direct, hybrid, and distributor-led models, adapting to local regulatory and market conditions. In India, through its hybrid model, the company caters to large hospitals, including Narayana Hrudayalaya Limited. In Europe, it has direct operations in major markets such as Germany, Spain, France and UK, successfully navigating complex regulatory and procurement environments. In certain other regions, such as Italy, it uses distributor-led models for efficient market entry and scaling. Its international revenue share has grown steadily over the past three years, reflecting increasing global acceptance and diversification of its business.
As on the date of this Red Herring Prospectus, it had three manufacturing facilities, two located in India and one in Thailand. Its integrated manufacturing facilities in India and Thailand give it a high level of control over the value chain, from components to finished products. By bringing key processes in-house such as the in-house manufacturing of balloon catheters, it has reduced costs, improved quality, and accelerated product development. This integration allows for faster prototyping and time to market, supporting its ability to innovate and respond quickly to emerging clinical needs.
According to the F&S Report, our products such as Supraflex Cruz (DES), Cocoon (Occluders) and Hydra (TAVI) are widely accepted in international markets, supported by endorsements from key opinion leaders (“KOLs”), successful government tender wins, and acceptance by major European Group Purchasing Organizations (“GPOs”). Deep engagement with KOLs has also influenced its product enhancement efforts. Its ability to meet the high standards of GPOs and secure large contracts in Europe and India further validates its products’ quality and clinical effectiveness, strengthening its reputation and driving global adoption.
SMTL has adopted a “House of Brand” approach, developing and manufacturing a portfolio of brands across product categories which are recognized for their clinical innovation. According to the F&S Report, its flagship brands – Supraflex Cruz (DES), Cocoon (Occluders), and Hydra (TAVI) – are widely accepted in international markets and are supported by endorsements from leading KOLs. As of June 30, 2026, it had overall 1596 employees in its three facilities (includes on-roll and off-roll).
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route secondary IPO of 13822116 equity shares worth Rs. 475.48 cr. at the upper cap. The company has announced a price band of Rs. 327 – Rs. 344 per equity shares of Re. 1 each. The issue opens for subscription on October 15, 2026, and will close on October 19, 2026. The minimum application to be made is for 43 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 13.60% of the post-IPO paid-up equity capital. This being a pure Offer for Sale (OFS), no funds are going to company. The issue is being made to provide exit to some of its stakeholders, and unlock the listing benefits.
The company has reserved 250000 equity shares for its eligible employees, and from the rest, it has allocated not more than 50% for QIBs, not less than 15% for HNIs, and not less than 35% for Retail investors.
The joint Book Running Lead Managers (BRLMs) to this issue are Motilal Oswal Investment Advisors Ltd., Avendus Capital Pvt. Ltd., HSBC Securities and Capital Markets (India) Pvt. Ltd., Nuvama Wealth Management Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Motilal Oswal Financial Services Ltd., Spark Institutional Equities Pvt. Ltd., Nuvama Wealth Management Ltd., are syndicate members.
Having issued initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 4 – Rs. 365 per share (on the basis of Re. 1 FV), between March 2009, and September 2026. The company also issued bonus shares in the ratio of 2 for 5 in May 2006. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 0.63, Rs. 6.00, Rs. 13.45, Rs. 46.40, Rs. 97.58, and Rs. 262.46 per share.
Post-IPO, its current paid-up equity capital of Rs. 10.16 cr. (101646778 equity shares) will stand same as this is a hundred percent secondary issue. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 3496.65 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit/ – (loss), of Rs. 908.59 cr. / Rs. – (7.35) cr. (FY24), Rs. 1035.96 cr. / Rs. 25.15 cr. (FY25), and Rs. 1218.73 cr. / Rs. 69.08 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 15.09 cr. on a total income of Rs. 354.33 cr. The company posted growth in its performances for the reported periods except for FY24, where it reported loss. Higher trade receivables of Rs. 306.56 cr. for Q1-FY27 raise concern. Its contingent liabilities stood at Rs. 10.76 cr. as of June 30, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 3.81 (basic) and an average RoNW of 6.14 %. The issue is priced at a P/BV of 5.35 based on its NAV of Rs. 64.35 as of June 30, 2026, as well as on the basis of post-IPO NAV per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 57.91. Based on FY26 earnings, the P/E stands at 50.59. The issue appears aggressively priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of – (0.82) % (FY24), 2.45% (FY25), 5.71% (FY26), 4.29% (Q1-FY27), and RoCE margins of 8.05%, 10.37%, 11.57%, 3.16%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has adopted a dividend policy in May 2025, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Poly Medicure, Laxmi Dental, as its listed peers. They are currently trading at a P/E of 52.0, and 31.1 (as of October 12, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The four BRLMs associated with this issue have handled 79 public issues in the past three fiscals, out of which 25 issues closed below the offer price on listing date.
CONCLUSION:
SMTL is engaged in manufacturing medical devices across vascular and structural heart intervention. Its products are well established and widely accepted world over, thus enjoys prime status as a first company in the world to receive a CE certification for DES. Because of product shift and other provisioning, it marked losses for FY24. With improved products in place and expanding its capacities, it is poised for better prospects ahead. Based on its recent average financial data, the issue appears aggressively priced. However, well-informed investors may park funds for long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
