
– By Dilip Davda
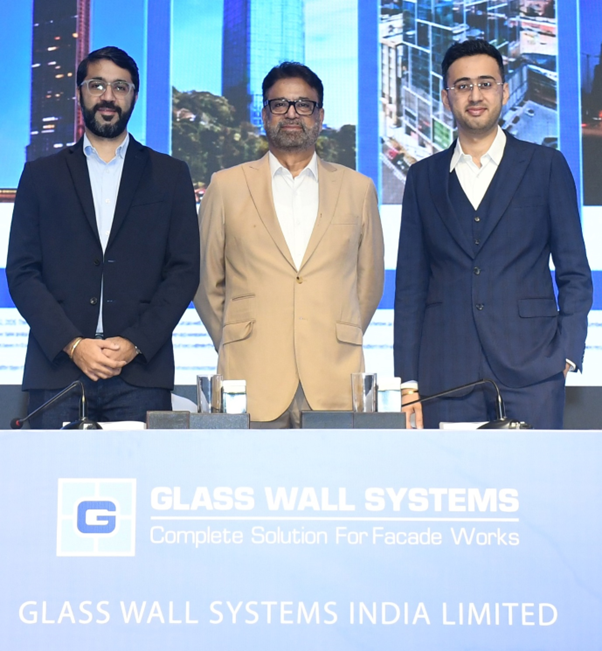
- The company is a premium façade solutions and fenestration provider in India, and across markets in USA, Australia.
- Though it witnessed fall in its top line for FY25, it marked growth in its bottom lines for all the three fiscals.
- Its overall order book stood at Rs. 981.55 cr. as of July 31, 2026.
- Its outperformance against listed peer is a bit surprising.
- Based on its recent average financial data, the issue appears greedily priced.
- Only well-informed/cash surplus investors may park moderate funds for long term.
ABOUT COMPANY:
Glass Wall Systems (India) Ltd. (GWSIL) is a premium façade solutions and fenestration provider in India and across markets in the USA and Australia. It is the second largest provider of façade solutions in India in terms of revenue in Fiscal 2025 and Fiscal 2024. (Source: Ken Report) The company is also India’s largest façade exporter in 2024 in terms of revenue. (Source: Ken Report) With over two decades of experience in the façade solutions industry, it has successfully completed 158 projects,
as of March 31, 2026, showcasing its expertise in delivering innovative solutions.
The façade and fenestration sector serves as the critical interface between a building’s interior and its external environment, combining advanced materials, precision engineering and architectural design to deliver both form and function. (Source: Ken Report) Façade solutions are integral components of modern architectural design, encompassing the exterior cladding of a building. (Source: Ken Report) Its façade solutions ensure the development of building exteriors that are both functional and visually appealing, while promoting sustainability and compliance with international standards, such as ASTM International and Australian / New Zealand standards. GWSIL’s offerings include curtain wall facades, storefront wall facades, unitized and semi-unitized curtain wall facades and frameless facades.
These systems are highly engineered products designed based on stringent technical specifications to provide stability and structural integrity to building frameworks. They enhance thermal efficiency, acoustic performance, and aesthetic appeal while ensuring structural integrity and durability. (Source: Ken Report) By driving growth through capacity expansion and backward integration, the company is well-positioned to enhance its operational efficiency, market competitiveness, and profitability. Its strategic approach ensures sustained success in both domestic and international markets. It provides a diverse array of innovative and customized products, including façade and curtain wall systems, bolted façades, skylights, canopies, and space frames, louvers, rain screen cladding, diagrids, and aluminium doors and windows.
The company offers comprehensive solutions through three primary areas: design and engineering, our manufacturing facility, and project management support. Its integrated approach ensures delivery of high-quality solutions tailored to meet the specific needs of clients. According to the Ken Report, it is youngest and the only company in India with such extensive integrated operations. (Source: Ken Report). As of July 31, 2026, its overall order book stood at Rs. 981.55 cr. As of March 31, 2026, it had 370 employees on its payroll, and additional 272 contract labourers.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO of approx. 23510425 equity shares (worth Rs. 427.89 cr.at the upper cap). The IPO consists of fresh equity shares worth Rs. 60.00 cr. (approx. 3296703 equity shares at the upper cap) and an Offer for Sale (OFS) of 20213722 equity shares (worth Rs. 367.89 cr. at the upper cap). The company has announced a price band of Rs. 172 – Rs. 182 per equity shares of Rs. 2 each. The issue opens for subscription on September 08, 2026, and will close on September 10, 2026. The minimum application to be made is for 82 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 26.74% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 50.00 cr. for capex on setting up of GPU project as part of planned backward integration, and the rest for general corporate purposes.
The joint Book Running Lead Managers (BRLMs) to this issue are IIFL Capital Services Ltd., and Motilal Oswal Investment Advisors Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Motilal Oswal Financial Services Ltd. is a syndicate member.
After issuing/converting initial equity shares at par value, the company has issued further equity shares at a price of Rs. 177.81 per share (based on Rs. 2 FV), in August 2025. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 3.57, Rs. 24.69, and Rs. 62.77 per share.
Post-IPO, its current paid-up equity capital of Rs. 16.93 cr. (84638550 equity shares) will stand enhanced to Rs. 17.58 cr. (87935253 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 1600.42 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 310.26 cr. / Rs. 20.25 cr. (FY24), Rs. 288.14 cr. / Rs. 57.51 cr. (FY25), and Rs. 471.43 cr. / Rs. 83.79 cr. (FY26). The company inconsistency in its top lines, while its bottom line posted surprising growth. Exceptional item worth Rs. 16.19 cr. resulted in a lower bottom line for FY24. Its contingent liability stood at Rs. 33.41 cr. as of March 31, 2026, that raises concern.
For the last three fiscals, the company has posted an average EPS of Rs. 7.32 and an average RoNW of 29.68 %. The issue is priced at a P/BV of 5.89 based on its NAV of Rs. 30.91 as of March 31, 2026, and at a P/BV of 4.98 based on its post-IPO NAV of Rs. 36.57 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 19.10. Based on FY25 earnings, the P/E stands at 27.83. The issue appears greedily priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 6.65% (FY24), 20.66% (FY25), 18.34% (FY26), and RoCE margins of 44.74%, 66.33%, 55.48%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has, for Class B equity shares, paid 2% dividend for FY24 and FY25, there after it skipped. It has already adopted a dividend policy in August 2025, based on its financial performance and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Innovator Façade Systems, as its listed peer. It is currently trading at a P/E of 15.9 (as of September 04, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash. GWSIL’s outperformance against its listed peer is a bit surprising.
MERCHANT BANKER’S TRACK RECORD:
The two BRLMs associated with this issue has handled 78 IPOs in the last three fiscals and out of which 23 IPOs closed below the issue price on listing date.
CONCLUSION:
GWSIL is a premium façade solutions and fenestration provider in India, and across markets in USA, Australia. Though it witnessed fall in its top line for FY25, it marked growth in its bottom lines for all the three fiscals. Its order book stood at Rs. 981.55 cr. as of July 31, 2026. Its outperformance against listed peer is a bit surprising. Based on its recent average financial data, the issue appears greedily priced. Only well-informed/cash surplus investors may park moderate funds for long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
