
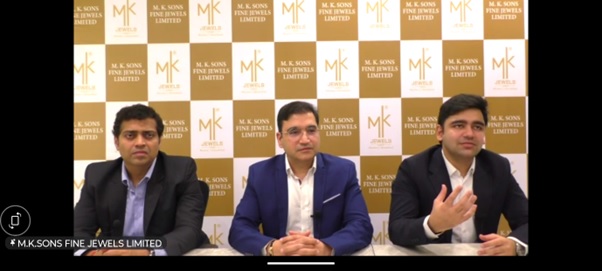
– By Dilip Davda
- The company is a retail focused jewellery company engaged in marketing and sale of gold/diamond/Cubic Zirconia jewellery in Mumbai and Ahmedabad.
- The company marked growth in its top and bottom lines for the reported periods.
- Based on its recent average financial data, the issue appears fully priced.
- Investors may park funds for medium to long term.
ABOUT COMPANY:
M. K. Sons Fine Jewels Ltd. (MKSFJL) is a retail-focused jewellery company engaged in the marketing and sale of a wide range of gold, diamond and Cubic Zirconia (CZ) jewellery through its own chain of retail showrooms since 2012. The Company acquired the proprietorship business of one of its Promoters, to consolidate operations under a single corporate entity through a Business Succession Agreement and to eliminate potential related party or partiality concerns, and align the business structure with the interests of a broader set of stakeholders.
The Indian gems and jewellery industry is a significant contributor to the national economy, accounting for approximately 7% of India’s GDP and around 15% of the country’s merchandise exports. India remains a global leader in diamond processing, accounting for over 90% of the world’s polished diamonds by volume, while also being one of the largest consumers of gold jewellery owing to its deep-rooted cultural, religious, and investment significance. (Source: Careedge Report).
The Company offers a diverse portfolio of contemporary and bridal designs with a focus on craftsmanship, design quality and customer-centric jewellery collections. It has established presence in the retail jewellery markets of Maharashtra and Gujarat by expanding its retail footprint across Mumbai and Ahmedabad, two key commercial centers in Western India. The Company currently operates three showrooms in Mumbai and two showrooms in Ahmedabad and has developed recognition as a regional jewellery brand in these markets. It is committed to serving the Western India market with jewellery certified by the Bureau of Indian Standards (BIS) Hallmark through its five showrooms located across Mumbai and Ahmedabad, with a total operational area of 6,513 square feet as on June 30, 2026.
Over the years, the Company has built a strong reputation and fostered customer trust in the region by offering high-quality, culturally resonant jewellery while adhering to ethical business practices. It caters to a broad and diverse customer base that places significant importance on quality, authenticity and craftsmanship. Its inventory sourcing is guided by a data-driven approach, enabling it to effectively respond to evolving customer preferences and changing market trends. MKSFJL procures its inventory from a network of suppliers located across the western region of India, primarily in Maharashtra and Gujarat, which provides flexibility in its supply chain and ensures the timely availability of products across its retail outlets.
While the company do not generally enter into long-term definitive agreements with suppliers, its procurement strategy allows it to maintain a steady and consistent flow of inventory aligned with customer demand. It offers 19442 SKUs under different collections, as of June 30, 2026. As of the said date, it was engaged with 70 wholesalers/manufacturers and 9 Karigar. As of September 30, 2026, it had 148 employees on its payroll.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route combo IPO of 17000000 equity shares worth Rs. 275.40 cr. at the upper cap. The IPO consists of 13600000 fresh equity shares (worth Rs. xx cr. at the upper cap), and an Offer for Sale (OFS) of 3400000 equity shares (worth Rs. xx cr. at the upper cap). The company has announced a price band of Rs. 153 – Rs. 162 per equity shares of Rs. 10 each. The issue opens for subscription on October 28, 2026, and will close on October 30, 2026. The minimum application to be made is for 91 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 30.20% of the post-IPO paid-up equity capital. From the net proceeds of the IPO, the company will utilize Rs. 152.83 cr. for funding inventory costs towards setting up of 1 new showroom, Rs. 30.00 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes.
The sole Book Running Lead Manager (BRLM) to this issue is Aryaman Financial Services Ltd., while Bigshare Services Pvt. Ltd. is the registrar to the issue. Aryaman Financial Services Ltd. Is also a syndicate member.
The company has issued its initial/major equity shares at par value; the company issued further equity shares in the price range of Rs. 176 – Rs. 200 per share between March 2012, and March 2025. It has also issued bonus shares in the ratio of 2 for 1 in May 2025, and 2 for 3 in December 2025. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 18.31 per share.
Post-IPO, its current paid-up equity capital of Rs. 42.69 cr. (42690760 equity shares) will stand enhanced to Rs. 56.29 cr. (56290760 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 911.91 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit, of Rs. 217.40 cr. / Rs. 8.17 cr. (FY24), Rs. 351.32 cr. / Rs. 23.26 cr. (FY25), and Rs. 538.86 cr. / Rs. 51.80 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 15.02 cr. on a total income of Rs. 101.45 cr. The company posted growth in its performances for the reported periods. Boosted margins from FY25 onwards raise eyebrows and concern over its sustainability going forward. Its contingent liabilities stood at Rs. 5.00 cr. as of June 30, 2026. Trade Receivables at Rs. 31.83 cr. as of June 30, 2026, raise concern.
For the last three fiscals, the company has posted an average EPS of Rs. 10.09 and an average RoNW of 28.17 %. The issue is priced at a P/BV of 3.78 based on its NAV of Rs. 42.88 as of June 30, 2026, and at a P/BV of 2.26 on the basis of post-IPO NAV of Rs. 71.66 per share at the upper cap.
If we attribute FY27 annualized super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 15.18. Based on FY26 earnings, the P/E stands at 17.61. The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 3.76% (FY24), 6.62% (FY25), 9.61% (FY26), 14.80% (Q1-FY27), and RoCE margins of 40.62%, 27.24%, 39.88%, 10.26%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has not paid any dividends for the reported periods of the offer document. It has adopted a dividend policy in March 2026, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Motisons Jewellers, Tribhovandas Bhimji, Senco Ltd., PNGS Reva, as its listed peers. They are currently trading at a P/E of 25.5, 21.2, 8.88, and 23.8 (as of October 23, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
This is the 13th issue from sole BRLM Aryaman Financial Services Ltd., in the last three fiscals. Out of the last 12 listings, 1 opened at discount, and the rest with premium ranging from 0.83% to 20% on the date of listing.
CONCLUSION:
MKSFJL is a retail focused jewellery company engaged in marketing and sale of gold/diamond/Cubic Zirconia jewellery in Mumbai and Ahmedabad. The company marked growth in its top and bottom lines for the reported periods. High volatility in bullion prices remains major concern for its future prospects. It is operating in a highly competitive and fragmented segment. Based on its recent average financial data, the issue appears fully priced. Investors may park funds for medium to long term.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
