
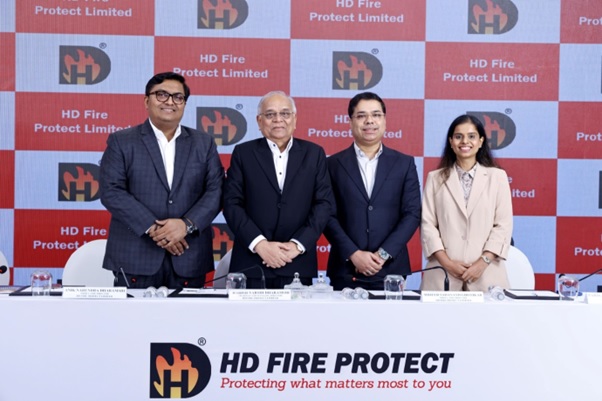
– By Dilip Davda
- The company is one of the leading Indian manufacturer and supplier of critical fire protection equipment and systems.
- Its domestic revenue is 65% and export earnings are 35% for the reported periods.
- The company has highest numbers of UL and FM approval certification.
- The company marked steady growth in its top and bottom lines for the reported periods.
- Based on its recent average financial data, the issue appears fully priced.
- Well-informed investors can park funds for medium to long term.
ABOUT COMPANY:
HD Fire Protect Ltd. (HFPL) is an Indian manufacturer and supplier of fire protection equipment and systems, offering a comprehensive portfolio spanning water, foam, and gas-based fire suppression systems, which are also generally known as firefighting products. The company develops majority of products in-house with proprietary designs to meet national and international standards, serving high-hazard industrial applications as well as residential and commercial sectors.
According to the CRISIL Report, it is the second-largest manufacturer of fire protection equipment and systems in India in terms of operating income (revenue from operations) in Fiscal 2025 and the largest exporter by value (equipment) in Fiscal 2025. The company’s export sales were in 49 countries as of the three months period ended June 30, 2026 and more than 90 countries as of Fiscal 2026. With more than three decades of experience, it has established itself as a globally recognized and reliable brand.
In the early 1990s, critical fire protection equipment and systems such as deluge valves, alarm valves, and medium velocity water spray nozzles were generally imported, with lack of Indian manufacturers offering high-quality alternatives like UL Listed and FM Approved products (Source: CRISIL Report). The Company is the first Indian fire protection equipment and systems manufacturer to receive UL Listing for deluge valves (1996) (Source: CRISIL Report). Since the commencement of its business, HFPL has consistently focused on providing locally manufactured fire protection equipment and systems as import-substitutes. It is also the first Indian fire protection equipment and systems manufacturer to receive FM approval for range of products used in low expansion foam system namely foam concentrates, bladder tanks, proportioners, topside discharge devices and foam water sprinkler discharge devices (Source: CRISIL Report).
Further, the company is also the first Indian company focused on fire protection equipment and systems manufacturing to receive ASME U (pressure vessels) stamp certification (Source: CRISIL Report). With 21 and 87 UL Listed and FM Approved certifications, as per UL product certifications and FM product certifications respectively, it has the highest number of UL Listed and FM Approved product certifications amongst the fire protection equipment focused peers in India as of September 2026 (Source: CRISIL Report).
As of June 30, 2026, its offerings are spread across 8 product categories, namely – (a) sprinklers, alarm valves and accessories, (b) deluge valves, deluge skids and pre-action systems, (c) foam equipment and suppression systems, (d) monitors and monitor nozzles, (e) systems valves and accessories, (f) water spray nozzles, (g) custom engineered systems, and (h) gas suppression systems, covering a wide spectrum of (a) industrial end use in sectors such as industrials, heavy engineering, aerospace, oil & gas, refining and petrochemicals, power & energy, pharmaceuticals, data centres, warehousing amongst others; and (b) residential and commercial end use in sectors such as hospitality, healthcare, retail, education, banking and warehousing. HFPL also empaneled with various customers across sectors where it has presence.
HFPL operates two manufacturing facilities in Maharashtra, Jalgaon MIDC and Thane MIDC, spanning a combined area of 8.50 acres. It has expanded the capacity of Jalgaon facility, with one unit for manufacturing and another for a dedicated fire test laboratory, industrial warehouse and R&D centre, admeasuring 2.50 acres, and are also constructing a warehouse at Wagle Estate, Thane, admeasuring 0.50 acres, which is expected to be completed by November 2026. In addition to its in-house production, the company also undertakes contract manufacturing of off-the-shelf products as well as white labelling to cater to diverse customer requirements. In Fiscal 2026, it supplied its fire protection equipment and systems to 2066 customers. The company supplied fire protection equipment and systems across 49 countries in the three-month period ended June 30, 2026, and across more than 90 countries between inception and March 31, 2026. This international reach is supported by a distributor-led supply chain for international markets and a Stockist model for India.
The company maintains a strong focus on quality, reflected in the absence of product recalls and a replacement rate of just 0.01% over the three months period ended June 30, 2026 and the past three fiscals. Its R&D initiatives are directed toward next-generation technologies that enhance performance, ensure environmental compliance, and meet global certification standards. The company also specializes in custom-engineered fire protection skids tailored to client-specific requirements and is the only Indian manufacturer to offer certain advanced systems, such as a next-generation pre-action system. HFPL’s innovation pipeline includes a new deluge valve design, for which a patent application is currently under process. As on the date of this Red Herring Prospectus, it holds patents in the United States of America, India, Turkey and Saudi Arabia for “pressure operated fluid valve with configurable diaphragm arrangement”, and two design registrations in India for “diaphragm of fire protection valve”. It has also made a patent application in the United Arab Emirates in respect of the same.
The company has supplied products at some of the key sites including master stream nozzle installations at India’s space launch pad at Srihari Kota, fire protection equipment (alarm valve, monitor, master stream nozzle) at India’s largest refinery at Jamnagar, fire protection equipment (drain valve, water flow detectors etc.) for the new Indian parliament building, fire protection systems (deluge valves) at Saudi Aramco’s Ras Tanura Sea Island site and fire protection equipment (deluge valves, sprinklers etc.) for Oman’s Integrated Power & Water Plant Project (Source: CRISIL Report). These projects highlight both the global acceptability and trust placed in its equipment and systems. It is both, India focused and export oriented, with a balanced revenue mix across domestic and international markets.
Its key export destinations include UAE, Saudi Arabia, Brazil, Turkey, Malaysia, and Indonesia. According to the management, they have emerged as the world leader in critical fire protect equipments and products and their revenue posted on an average 65% domestic and 35% global earnings for the reported periods. This ratio will continue going forward and also enjoys most preferred supplier of critical fire protection systems status. This segment has many entry barriers and thus, it does no see any major threat on competition aspect. As of June 30, 2026, it had 279 employees on its payroll, and additional 253 contract workers in various department. As of the said date, its order book stood at Rs. 158.60 cr.
ISSUE DETAILS/CAPITAL HISTORY:
The company is coming out with its maiden book building route secondary IPO of 26284500 equity shares worth Rs. 712.31 cr. at the upper cap. The company has announced a price band of Rs. 258 – Rs. 271 per equity shares of Rs. 5 each. The issue opens for subscription on October 13, 2026, and will close on October 15, 2026. The minimum application to be made is for 55 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 15% of the post-IPO paid-up equity capital. This being a pure Offer for Sale (OFS), no funds are going to company. The issue is being made to provide exit to some of its stakeholders, and unlock the listing benefits.
The company has reserved 64576 equity shares (worth Rs. 1.75 cr. at the upper cap) for its eligible employees, and offering them a discount of Rs. 25 per share. From the rest, it has allocated not more than 50% for QIBs, not less than 15% for HNIs, and not less than 35% for Retail investors.
The joint Book Running Lead Managers (BRLMs) to this issue are Ambit Pvt. Ltd., Anand Rathi Advisors Ltd., and IIFL Capital Services Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. Ambit Capital Pvt. Ltd., and Anand Rathi Share & Stock Brokers Ltd. are syndicate members.
Having issued/converted initial equity shares at par value, the company has issued bonus shares in the ratio of 2 for 1 in November 2023, 2 for 1 in July 2024, and 10for 1 in March 2025. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. NIL, Rs. 0.05, and Rs. 0.09 per share.
Post-IPO, its current paid-up equity capital of Rs. 87.62 cr. (175230000 equity shares) will stand same as this is a hundred percent secondary issue. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 4748.73 cr.
FINANCIAL PERFORMANCE:
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit, of Rs. 392.02 cr. / Rs. 87.92 cr. (FY24), Rs. 450.68 cr. / Rs. 109.72 cr. (FY25), and Rs. 505.12 cr. / Rs. 116.79 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 23.87 cr. on a total income of Rs. 114.07 r. The company posted growth in its performances for the reported periods. Rising trade receivables year-on-year raise concern. Its contingent liabilities stood at Rs. 9.61 cr. as of March 31, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 6.25 and an average RoNW of 29.05 %. The issue is priced at a P/BV of 11.88 based on its NAV of Rs. 22.82 as of June 30, 2026, as well as on the basis of post-IPO NAV per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 49.72. Based on FY26 earnings, the P/E stands at 40.69. The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 22.43% (FY24), 24.35% (FY25), 23.12% (FY26), 20.92% (Q1-FY27), and RoCE margins of 37.61%, 39.63%, 40.33%, 8.36%, respectively, for the referred periods.
DIVIDEND POLICY:
The company has paid a dividend of 20% (FY24), 805% (FY25), 100% (FY26). It has adopted a dividend policy in July 2026, based on its earnings and future prospects.
COMPARISON WITH LISTED PEERS:
As per the offer document, the company has shown Azad Engg., KSB Ltd., Kirloskar Pneumatic, Elgi Equipment, Ingersoll-Rand, as its listed peers. They are currently trading at a P/E of 134.0, 51.5, 31.9, 39.4, and 45.8 (as of October 08, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
MERCHANT BANKER’S TRACK RECORD:
The three BRLMs associated with this issue have handled 74 public issues in the past three fiscals, out of which 20 issues closed below the offer price on listing date.
CONCLUSION:
HFPL is one of the leading Indian manufacturer and supplier of critical fire protection equipment and systems. Its domestic revenue is 65% and export earnings are 35% for the reported periods. The company has highest numbers of UL and FM approval certification. Its order book stood at Rs. 158.60 cr. as of June 30, 2026. The company marked steady growth in its top and bottom lines for the reported periods. Based on its recent average financial data, the issue appears fully priced. Well-informed investors can park funds for medium to long term in this dividend paying company.
Review By Dilip Davda on August, 2026
Review Author
DISCLAIMER: No financial information whatsoever published anywhere here should be construed as an offer to buy or sell securities, or as advice to do so in any way whatsoever. All matter published here is purely for educational and information purposes only and under no circumstances should be used for making investment decisions. My reviews do not cover GMP market and operators game plans. Readers must consult a qualified financial advisor before making any actual investment decisions, based the on information published here. With entry barriers, SEBI wants only well-informed investors to participate in such offers. With crazy listings in the recent past, SME IPOs drew the attention of investors across the board and lead to seer madness. However, as SME issues have entry barriers and continued low preference from the broking community, any reader taking decisions based on any information published here does so entirely at their own risk. The above information is based on information available as of date coupled with market perceptions. The Author has no plans to invest in this offer.
About Dilip Davda
Dilip Davda is veteran journalist associated with stock market since 1978. He is contributing to print and electronic media on stock markets/insurance/finance since 1985.
Dilip Davda is a leading reviewer of public issues and NCDs in the primary stock market in India. The knowledge he gained over 3 decades while working in the stock market and a strong relationship with popular lead managers makes his reviews unique. His detailed fundamental and financial analysis of companies coming up with IPOs helps investors in the primary stock market. Dilip Davda has a special interest in analyzing the SME companies and writing reviews about their public issues. His reviews are regularly published online and in news papers.
(Dilip Davda -SEBI registered Research Analyst-Mumbai,
Registration no. INH000003127 (Perpetual)
Email id: dilip_davda@rediffmail.com ).
